UK gambling market grows to £17.5bn as online dominates and retail declines
The Gambling Commission reports 4.4% annual GGY growth driven by online sectors while physical gambling premises continue their long-term contraction, with proposed regulatory changes threatening further retail decline.
The UK gambling industry reached a record £17.5 billion in gross gambling yield (GGY) during the 2025-2026 financial year, according to comprehensive data released by the Gambling Commission. The 4.4% year-on-year growth underscores the sector's resilience amid economic uncertainty, though the market continues to undergo significant structural changes as consumer preferences shift decisively toward digital platforms. When excluding all reported lottery activity, which traditionally accounts for a substantial portion of gambling participation, the core gambling market grew even faster at 4.7% to £13.2 billion.
Online gambling becomes industry powerhouse
Remote gambling activities have solidified their position as the driving force behind the industry's expansion, generating £8.3 billion in GGY - a robust 6.9% increase that represents approximately 63% of all non-lottery gambling revenue. Online casinos emerged as the clear leader within this segment, producing £5.7 billion in annual yield. Slots dominated the digital casino landscape with £4.8 billion, suggesting these games continue to capture the majority of player spending in virtual environments. The strength of remote gambling was particularly evident in the first quarter of 2026, where online verticals generated £2.2 billion, with remote casino alone accounting for £1.5 billion (68.3%) of that total.
Sports betting maintained its position as the second-largest online category at £2.4 billion, though its growth trajectory appears more modest compared to casino products. Football betting led this segment with £1.2 billion in yield, followed by horse racing at £769.3 million - figures that reflect the enduring popularity of these sports among British punters. Remote bingo, while significantly smaller at £147.8 million, demonstrates how even traditionally land-based activities are finding their digital audience.
Retail sector faces mounting challenges
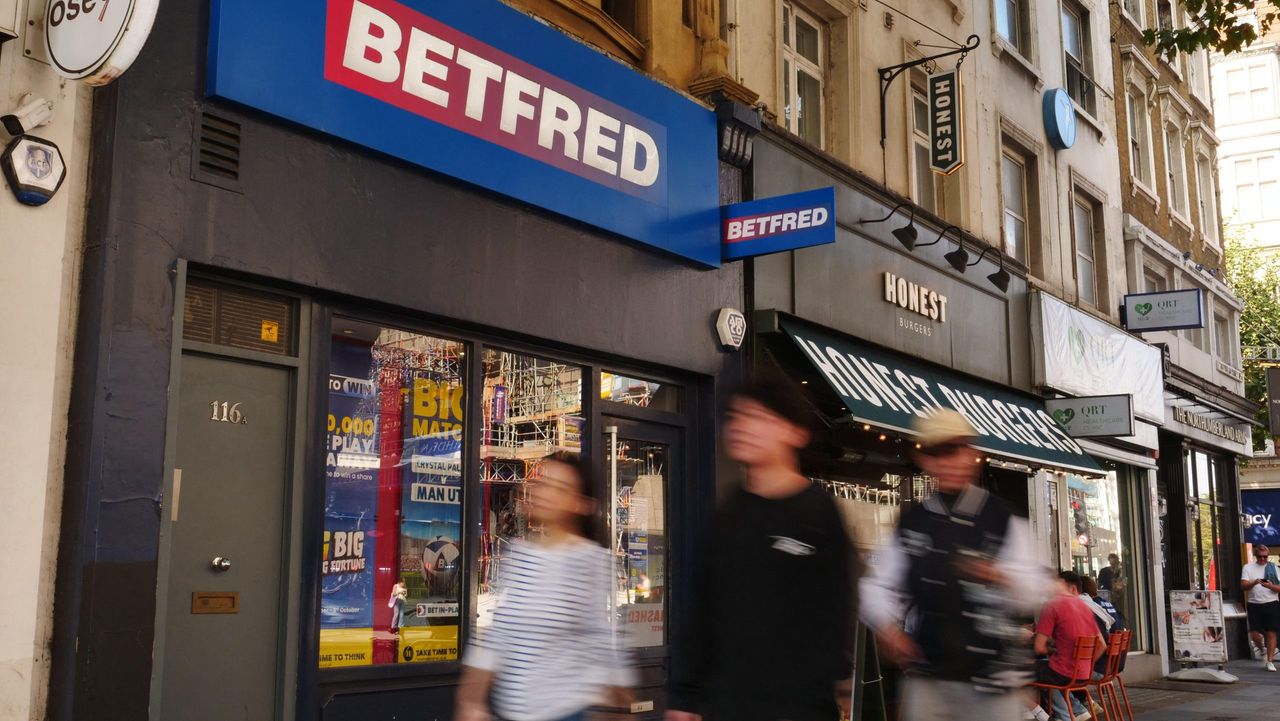
The land-based gambling sector posted a marginal 1.1% increase to £4.9 billion in GGY, failing to keep pace with the broader market's expansion. This underwhelming performance coincided with a 2% reduction in the UK's physical gambling estate, which now stands at 8,081 licensed premises. Betting shops bore the brunt of this contraction, declining for the twelfth consecutive reporting period to 5,617 locations - a loss of 208 shops (3.6%) year-on-year. Major retail operators including William Hill and Betfred have implemented substantial restructuring programs, closing hundreds of shops between them as they rebalance their operations toward digital channels.
Non-remote betting declined 3.3% to £2.4 billion, while traditional casinos managed modest 0.4% growth to £933.9 million. Bingo halls emerged as a rare bright spot in the retail landscape with an 8.2% increase to £703.8 million, potentially benefiting from their social experience that proves harder to replicate online. The mixed fortunes across retail categories highlight how different gambling formats are responding to changing consumer behaviors and competitive pressures from digital alternatives.
Gaming machines show resilience amid regulatory uncertainty
Gaming machines demonstrated surprising strength in arcades and adult gaming centers (AGCs), generating £800.1 million in GGY - a 10.7% annual increase. AGCs accounted for £761.4 million of this total, reflecting an even stronger 11.3% growth rate. Across all licensed premises, gaming machines contributed £2.7 billion to industry yield, representing a 4.3% uplift. The total number of machines stood at 191,804 in the final quarter, suggesting operators continue to view them as vital revenue generators despite growing regulatory scrutiny.
Prime Minister Andy Burnham has proposed sweeping changes that could significantly impact this sector, including repealing the "aim to permit" rule that currently facilitates the opening of betting shops and 24-hour slot machine arcades. Under the new proposals, AGCs offering round-the-clock access to gambling machines would require planning approval, potentially creating substantial barriers to operation. The government is also considering increased taxation on gaming machines following recommendations from the Social Market Foundation, with possible measures appearing in the upcoming autumn budget.
Lottery sector maintains steady growth
The National Lottery reported £7.9 billion in ticket sales, marking a 0.9% increase despite a slight 0.6% reduction in prize payouts to £4.5 billion. Contributions to good causes grew 2.8% to between £1.6 billion and £1.7 billion, underscoring the Lottery's continued importance as a funding mechanism for charitable and community initiatives. Large society lotteries experienced more vigorous growth with ticket sales up 5.7% to £1.2 billion, prize payouts increasing 6.1% to £335.6 million, and contributions rising 2.8% to £498.5 million.
Participation patterns reveal evolving market dynamics
The Gambling Commission's annual survey of 5,277 adults between January and May 2026 revealed stable overall participation rates, with 49% reporting gambling activity in the past four weeks - consistent with previous years. When excluding lottery-only players, participation stood at 28%, suggesting about 21% of adults engage exclusively in lottery products. The data highlights the divergent trajectories of different gambling formats, with online participation reaching 39% (16% excluding lottery players) compared to 29% for in-person gambling (18% excluding lottery players).
Scratchcards emerged as the most popular non-lottery activity at 13%, followed by betting at 10% and online instant win games at 8%. Gender disparities remain pronounced in sports betting, with 16% of men reporting participation compared to just 4% of women. Age analysis showed overall gambling participation peaking among 45- to 64-year-olds (56%-59%), while the 35-44 demographic showed the highest engagement when excluding lottery play (35%). Motivations centered on entertainment and the prospect of large winnings, with 42% of respondents expressing positive feelings about their most recent gambling expenditure.
Industry structure reflects digital transition
As of 31 March 2026, the UK gambling market comprised 2,154 licensed operators (down 1.1%) but 3,097 separately licensed gambling activities (up 0.4%). This subtle divergence suggests operators are consolidating while simultaneously diversifying their service offerings, likely in response to both market opportunities and regulatory requirements. The figures underscore how the industry continues to evolve its operational models to adapt to digital dominance and changing consumer expectations.